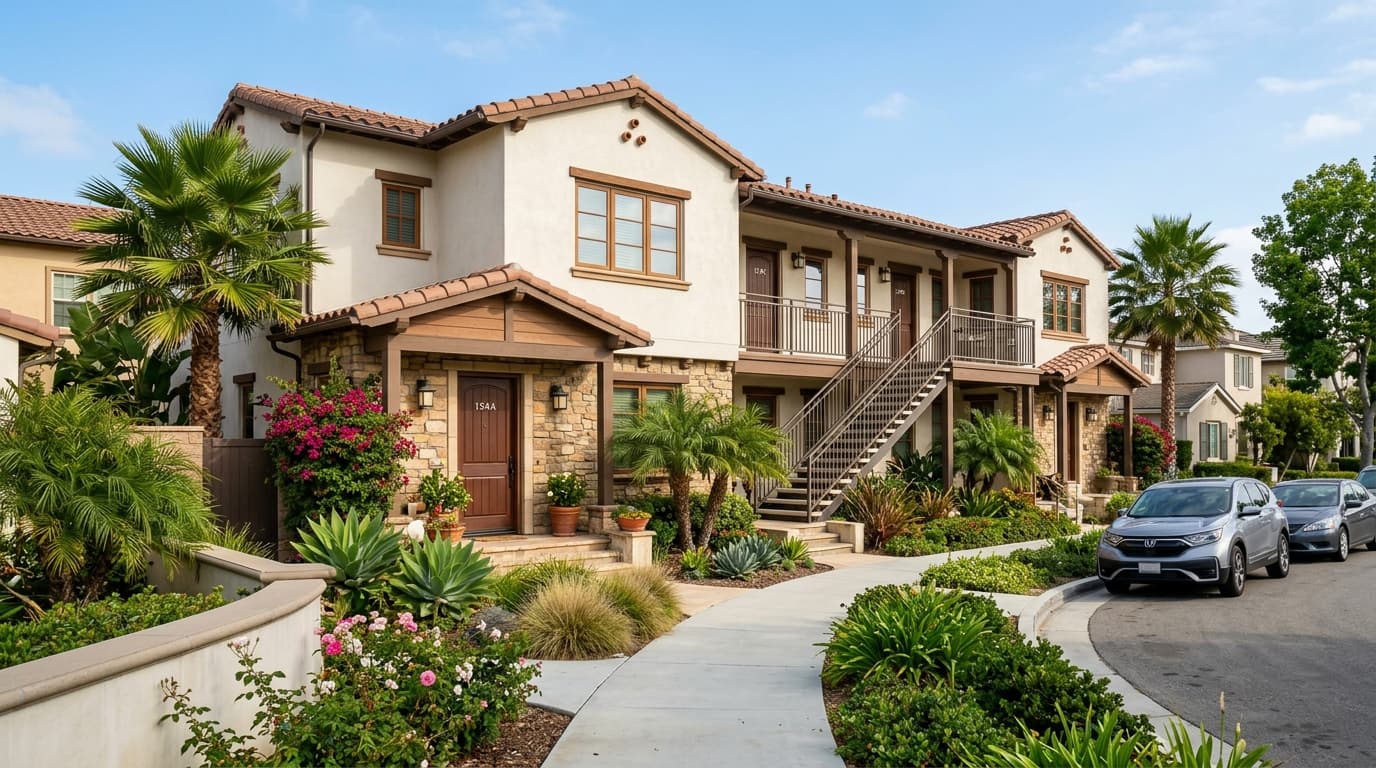
Real Estate Investing 101: House-Hacking and Multi-Family Properties
By Ben Cat · DRE #02030696 · NMLS #15970783 min read
Buying a two- to four-unit property and living in one unit can lower your housing cost and build equity. Here is how the math and financing work.
House-hacking is one of the most accessible ways to begin investing in real estate. The idea is simple: buy a property with two to four units, live in one, and rent out the others. The rent helps cover your mortgage, which can reduce your housing costs while you build equity.
Why Owner-Occupants Have an Advantage
When you live in the property, you can qualify for owner-occupant financing, which usually carries lower down payments and better rates than investor loans. FHA loans, for example, may allow as little as 3.5 percent down on a one- to four-unit property you intend to occupy, subject to credit, income, and program requirements. Conventional loans also offer owner-occupant options. Compare programs with your lender, since requirements and costs differ.
Two Metrics Every Beginner Should Know
Gross Rent Multiplier (GRM) is the purchase price divided by annual gross rental income. A lower GRM suggests you are paying less for each dollar of rent, but it ignores expenses, so use it only as a quick screening tool.
Net Operating Income (NOI) is annual rental income minus operating expenses, excluding mortgage payments. Operating expenses include property taxes, insurance, maintenance, property management, utilities you pay, and a vacancy allowance. NOI shows how much income the property produces before debt service, and it is the foundation for deeper analysis such as capitalization rate and cash flow.
A Simple Illustration
Suppose a fourplex produces $9,000 per month in total rent, or $108,000 per year. After accounting for vacancy, taxes, insurance, repairs, and other costs, NOI might come to a fraction of that figure. Compare NOI with your annual mortgage payments. If NOI exceeds your payments, the property generates positive cash flow; if not, you will need to cover the difference from other income. This example is for illustration only, so build your own numbers from real quotes and actual rents.
Do Not Forget Reserves and Realistic Expenses
New investors often underestimate costs. Budget for:
- Vacancy between tenants
- Repairs and capital expenditures such as roofs and water heaters
- Property management, even if you plan to self-manage
- Landlord insurance and any required licenses
- Compliance with California tenant laws, including notice rules and rent regulations
Evaluate the Property and the Location
Look for strong rental demand, reasonable condition, and legally permitted units. Confirm that each unit is permitted and properly documented, because unpermitted units can create financing and legal problems. Learn local rental rates by reviewing comparable listings, and inspect each unit carefully.
Steps to Get Started
- Check your credit, savings, and income to understand loan options.
- Decide how much work you are willing to do as a landlord.
- Review properties using GRM for screening and NOI for deeper analysis.
- Get a verified pre-approval for owner-occupant financing.
- Perform thorough inspections and review leases, rents, and financial records.
Risks to Understand
Rents can fall, tenants can leave, and expenses can rise. Leverage magnifies both gains and losses, so keep a healthy cash reserve and avoid stretching to the maximum price a lender will approve.
Plan Your Exit Strategy
Every investment should have an exit plan. Many house-hackers eventually move out and keep the property as a full rental, while others sell and use the proceeds toward a larger purchase. Some use tax-deferred exchange strategies, which require careful timing and professional guidance. Think about how long you plan to hold, what market conditions would cause you to sell, and what your options are if your life changes. A plan made before you buy is far easier to execute than one improvised under pressure.
Start With the Right Tools
Download the Multi-Family Property Evaluation Worksheet at benvcat.org to practice with real numbers, then connect with Ben Cat to discuss financing options and Orange County properties that may fit your first investment.
This article is for general educational purposes and is not investment, tax, or legal advice. Ben Cat, DRE #02030696, NMLS #1597078, Century Financial Group, Corp., DRE #01930905.
- #house hacking
- #multi-family
- #FHA
- #investing
- #rental property
By Ben Cat, California Real Estate Salesperson (DRE #02030696) and Mortgage Loan Originator (NMLS #1597078), brokered by Century Financial Group, Corp. (DRE #01930905).
General information only, not legal, tax, or investment advice, and not an offer or commitment to lend. All loans are subject to credit and underwriting approval. Equal Housing Opportunity. Compare loan options · Disclosures.